
Who feels the pain from the bond sell-off?

Who feels the pain from the bond sell-off?
With prices plunging and yields at decade highs, these are the parts of the financial system that could come under strain. A sell-off in global bond markets has pushed borrowing costs to their highest levels in a decade or more. That means potentially heavy losses for banks, insurers, pension funds and asset managers that own trillions of dollars of sovereign and corporate debt after loading up in recent years. Policymakers and investors are wary that the latest round of sharp moves could inflict severe damage on various parts of the financial system.
Paper losses on the most opaque part of US banks’ bond portfolios are now close to 400 billion USD — an all-time high, and 10% above the peak at the start of the year that caused the collapse of Silicon Valley Bank. Most banks, and in particular the largest ones, will not have to sell and so will never realise those losses. But the implosion of midsized US lender SVB in March refocused the minds of regulators and investors on the risks lurking in bank bond portfolios.
After receiving an avalanche of deposits from venture capital funds, SVB ramped up investment in a 120 billion USD portfolio of highly rated government-backed securities. But when rates rose sharply last year, the value of the portfolio fell by 15 billion USD, which was almost equal to the bank’s total capital, making it vulnerable to a wave of customers pulling their deposits. At the same time, higher rates create more incentive for depositors to move their money, forcing banks to pay up to keep accounts — which ultimately hurts profits.
Shares of Western Alliance Bancorp, a Phoenix-based regional bank that like the former SVB caters to cash-challenged start-ups, have fallen 20% since bond yields began their renewed rise in late August. Among the big banks, Bank of America has been the worst performer. Shares of BofA — which at the end of the second quarter had nearly 110 billion USD in unrealised losses, the most out of any bank in the US — hit a 52-week low on Wednesday of just below 26 USD. In all, the shares of the US’s largest banks, as measured by the KBW Nasdaq Bank index, have dropped an average of 8.5% in the past month, erasing tens of billions of dollars from investors’ portfolios.
Life insurers are big holders of bonds, which they use to back liabilities such as pension obligations. Their share prices were hit hard following the collapse of SVB. Insurers can often hold bonds to maturity, riding out market falls, while higher interest rates generally lift their solvency levels. But the concern is that a speedy rise in rates encourages customers to cash in long-term products, forcing insurers to sell bonds and other matching assets at a loss. The worst-case scenario is that “policyholder behaviour changes such that the insurers become forced sellers”, said Douglas Baker, a director at Fitch Ratings.
At the end, the rising cost of debt has dramatically lowered interest coverage ratios across the private equity universe, a metric that many lenders and rating agencies use as a gauge of whether companies can service their debts with operating profits. Together with inflation and a slowing economy, that could lead to more buyout-backed companies running into trouble. Rising long-term interest rates will also put pressure on private real estate valuations, where firms such as Blackstone and Brookfield have become some of the largest property owners globally. Private real estate valuations have traditionally been done using benchmark rates of 10 years or longer, which up until recent months had risen far less than short-term rates. Were longer term rates to stay high for a prolonged period, it may force property owners to cut valuations anew just as trillions of dollars in loans are due to mature in the coming years.
Double trouble: A Strong Dollar and Rising Oil Prices
An intense period of rising interest rates, high oil prices and a stronger dollar is pushing the financial market consensus on US economic growth away from the comforting notion of a soft landing. There were three important Central Bank comments over the week that stood out. Firstly, San Francisco Fed President Daly noted that the rise in yields in September “is equivalent to about a rate hike” and that the Fed can hold rates steady if the cooling of the labor market and inflation continues. Second, Richmond Fed President Barkin said that “we have time to see if we’ve done enough or whether there’s more work to do”. Then finally, the ECB’s Villeroy said the increase in bond yields may be excessive, but it is helping to tighten financing conditions. The subtle pushback initially helped global interest rates stabilize, but the strong NFP release, with prior month revisions, strengthened the higher-for-longer narrative.
Crude oil was notably volatile around OPEC and technical CTA-related flows, having declined c.12% over the week and is well below the 50-day moving average, just as copper fell to a four-month low. Understandably this caused the S&P 500 to fall to a four-month low, having lost 8% since the peak in late-July, which also puts the ETF (SPY) close to the 200-day moving average. Spreads in U.S. High Yield markedly increased, with CDX HY above 500bps once again. Central banks in Australia and New Zealand held interest rates unchanged, along with India, but Poland cut by 25bps and Sri Lanka by 100bps. However, it was the rumored FX intervention in the Japanese yen that had market participants guessing. There was no official comment from the Japanese Ministry of Finance, which gave way to plenty of conspiracy theories.
However, the trigger points in global FX were concerning given the ascent in DXY to a 10-month high and EUR falling to its lowest level against USD since December. These trends partially corrected toward the end of the week, but headlines were still made. In that regard, the 30-year U.S. Treasury rose above 5.0% for the first time since 2007. Fitch downgraded Panama to BBB- with a negative outlook, just as Moody’s downgraded Egypt to Caa1. The latter caused sizeable volatility on Friday, which will become an important talking point into IMF/World Bank meetings in Morocco next week. Similarly, the consternation around whether the EU will release 13 billion EUR in funding to Hungary that the block had frozen last year was equally topical. Finally, Turkish inflation came in at 61.5% with core CPI elevated at 68.9%, although the release may be overshadowed by geopolitics after the U.S. shot-down one of its drones in Kurdistan.
Benjamin Netanyahu warns Israel faces ‘long and difficult’ war
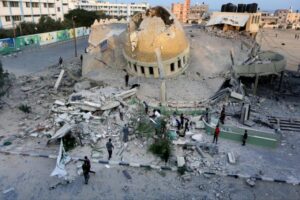
Planes strike Gaza overnight after unprecedented attack by Hamas militants. Benjamin Netanyahu warned that Israel faced a “long and difficult war” as its forces continued to wage gun battles with Palestinian militants on Sunday morning after an unprecedented multipronged attack by Hamas that stunned the country. More than 200 Israelis have been killed, 1,800 injured and 100 taken hostage, Israeli officials said, after hundreds of militants on paragliders, motorbikes and boats stormed into the country from the Gaza Strip in a surprise attack that inflicted Israel’s worst death toll in decades.
Israel responded with a huge bombardment of Gaza which continued overnight, levelling multistorey buildings, as well as hitting targets in Lebanon after the Iran-backed Hizbollah militant group fired mortars towards Israel. Israel also cut off the supply of electricity, fuel, and goods to Gaza, which it and Egypt have subjected to a crippling economic blockade since Hamas took control in 2007. Officials in Gaza said on Sunday morning that 313 people had been killed by Israeli strikes on the coastal enclave and that 1,990 had been wounded.
Speaking after a meeting of the Israeli security cabinet early on Sunday morning, the Israeli prime minister said Israeli forces had destroyed the “vast majority of the enemy forces that infiltrated our territory”, and that it had now begun the “offensive phase”. “[This] will continue with neither limitations nor respite until the objectives are achieved,” he said. However, on Sunday morning, 24 hours after the attack began, Israeli forces were still battling militants, and an official said that fighting was continuing in eight places in Israel, including at a military base in Zikim.
Hamas said its gunmen were still engaged in clashes in several areas in Israel and were being supported by rocket fire. In a sign of the potential for the conflict to spiral into a regional conflagration, Israel’s military said that its artillery had also struck areas in Lebanon after Hizbollah said that it had fired mortars towards Israel “in solidarity” with the Palestinian people. Richard Hecht, a spokesman for Israel’s armed forces, said the military was looking into the incident but that it had not been an “all out” attack from Lebanon, and urged Hizbollah, which has a strong presence in southern Lebanon, not to enter the fighting. “I don’t think they will. But if they do, we are ready,” he said.
However, despite the outrage in Israel at the security failures, there were also signs of the main political parties closing ranks, with Netanyahu and the leaders of the two largest opposition parties, Yair Lapid and Benny Gantz, discussing forming a unity government for the duration of the conflict, which would focus narrowly on security issues. Israeli officials said that militants in Gaza had fired more than 3,500 rockets at Israel during their initial barrage on Saturday, but that most casualties had been caused by close combat and “executions” by Hamas militants. The UN Security Council was due to meet later on Sunday amid international efforts to de-escalate the conflict. The secretary-general António Guterres, condemned the attack by Hamas and urged “all diplomatic efforts to avoid a wider conflagration”, while the UN peacekeeping force had been deployed along Israel’s border with Lebanon to “maintain stability and help avoid escalation”.
India’s smartphone market set to surge
With a thriving economy and demographic shifts driving consumer demand, the market could triple to 90 billion USD by 2032. India is on track to become the world’s third-largest economy by the end of the decade, propelled by increased digitalization and a burgeoning consumer class. The same forces are setting up the country of more than 1 billion people to be the fastest-growing smartphone market in the world in the next 10 years. After 20 years of lagging behind its global peers, India's smartphone market now looks set to reach its potential. It is expected that the market will triple from current levels to reach 90 billion USD by 2032.
Despite leading the world in terms of population growth this year, India has thus far failed to deliver on investors' long-held expectations of significant growth opportunities for smartphone usage. Market penetration has languished at around 40%, compared with the global average of 60%, while most of the growth in the market has come from cheaper, lower-end devices. But smartphone usage appears poised to surge, along with upgrades to the newest and most expensive phones. India’s GDP is expected to more than double over the next decade, reaching 7.5 trillion USD with expected annual growth of 6.6%. At the same time, per-capita income is expected to double, and the country is projected to have five times as many high-income households by 2031.
These factors, along with rising urbanization and improvements in infrastructure, are expected to drive 11% annual growth in the smartphone market over the next decade. This would make India’s market the third-largest in the world after China and the U.S., accounting for 15% of global market value, up from 6% today. In this scenario, India would be the sole growth driver in the global smartphone market in the next decade, ultimately accounting for 20% of worldwide shipments by 2032.
Stay up to date
More Newsletter to Check



SUBSCRIBE TO NEWSLETTER
Subscribe to download our daily economics and business roundup


×
![]()