
Inflation records are meant to be broken

Inflation records are meant to be broken.
Eurozone inflation rose to 8.6% from 8.1% in May, just as Spanish and French inflation hit multi-year highs 10.2% and 5.8%, respectively.
Global interest rates rallied over the past week by 10-25bp across Europe and the U.S., while commodities sold-off in an aggressive fashion and recessionary risks became more prevalent. Even major cryptocurrencies were down 8-15%, with Bitcoin below 19,000 USD momentarily.
Themes over the week include: (1) China’s rebound with a jump in non-manufacturing PMIs to 54.7 for June from 47.8 previously; (2) Colombia’s largest rate hike in over 20 years (150bp) to 7.5% as inflation hit 9.1%; (3) South Africa’s SARB was seen as credible with Governor Kganyago guiding a 50bp hike in July, but load shedding is weighing on FX along with the broader commodity sell-off; (4) Hungary aggressively hiked rates by 185bp relative to consensus of 50bp, although the NBH sought to simplify the interest rate policy framework; and (5) the ECB’s Sintra forum offered a more hawkish impression of what to expect over the summer period and the pace of tightening both in July and September. As these events unraveled, the Fed’s Atlanta nowcast GDP moved to -1.0% for 2Q having previously been at 0.3%, which added to the stagflation-cum-recession theme. This was fueled further by the weak U.S. ISM readings.
Moving to our EM update, Emerging market sovereign credit ended the week down 1.5% with spreads 36bp wider. However, the relative strength in EM corporate credit was telling and only down 0.4% with spreads widening 19bp. Outperformers over the week were Croatia, Malaysia and China while Sri Lanka, Ukraine and Zambia underperformed. The move in U.S. Treasuries had also become notable, as the 2-year note broke through its support level and the June 2023 Eurodollar contract (EDM3) traded above its downtrend line. These technical features contributed to a rally as the peak inflation narrative gathered further momentum after the recent PCE release (despite trends in Europe).
Fears of recession leave 40 billion EUR of European corporate bonds in distress
Rating agency S&P warns of ‘increasingly murky outlook’ for region’s credit market
More than 40 billion EUR of European corporate bonds are now trading at distressed levels, highlighting how the worsening economic outlook has triggered rising angst about companies’ ability to pay their debts. The pile of euro-denominated corporate bonds flashing warning signs has jumped from 6 billion EUR at the end of 2021. The stock of distressed corporate debt more than doubled from May 31 to June 30 alone, underscoring how quickly concerns are mounting that central banks’ decisions to tighten monetary policy could tilt major economies into recession. Investors are also fretting that high levels of inflation will increase companies’ cost of doing business.
Credit ratings are likely to come under pressure into 2023 as supply constraints keep food and energy prices elevated, households increasingly struggle with falling real incomes, and central banks prioritize inflation over growth. Bonds trading at distressed levels — with a yield above government benchmarks, or spread, of more than 10 percentage points — now account for 8.8% of the Ice index of euro-denominated junk bonds, compared with 1.3% at the end of 2021. This shows investors are pricing in the chance they will not receive money when bonds mature, pushing up the yield of companies’ bonds.
Meanwhile, the iTraxx Crossover, which tracks the cost of junk bond credit default swaps — insurance-like products that protect against defaults on Europe’s riskiest bonds — has risen to levels last seen in April 2020. The lack of demand for riskier bonds suggests Europe’s least creditworthy businesses could struggle to refinance debt and will have to guarantee higher returns to investors to attract funding.
Jose Antonio Ocampo, an orthodox economist with strong market credentials, appointed Colombia’s Finance Minister
Colombia’s President-Elect Gustavo Petro named Jose Antonio Ocampo, one of the country’s most highly respected economists, as his finance minister.
Jose Antonio Ocampo was most recently an economics professor at Columbia University in New York and Co-Director of the Central Bank and has already served as Colombia’s Finance Minister in the late 1990s. His reputation of a brilliant orthodox economist will likely reassure markets that have been concerned about the trajectory of Colombia’s economic policy under Petro, who will become the country’s first left-wing president in its modern history, when he assumes office on August 7. Besides his strong market credentials, Mr. Ocampo was also a vocal critic of Mr. Petro’s fiscal spending plans during the pre-election period, which might signal that the President-Elect would prefer a more conservative government spending approach once in office.
In addition to the credit-positive appointment of Mr. Ocampo, Mr. Petro has also reached out to and met with his main political opponent from the right-wing of Colombia’s political spectrum, former president, Alvaro Uribe. We construe this as another constructive sign that “building bridges” around key policy/political issues seem to be one of Petro’s priorities, at least in the early days of his Administration. Putting all of this together, we see a window of opportunity in which markets should give the new Petro Administration the “benefit of the doubt” in terms of economic policy, potentially setting the stage for a general recovery in Colombian assets that have been trading at historic high-risk premiums versus peers.
China June PMIs move back into expansionary territory
NBS composite PMI jumped 6pts to 54.1 with the non-manufacturing index leading the gains at 54.7 and manufacturing at 50.2 The price input and delivery components continued to show multi-point improvements reflecting easing of supply constraints in context of reduced COVID restrictions.
The data suggests that the gradual recovery remains intact as virus related measures have been eased (roughly 9% of GDP vs. peak of ~35% of GDP) and incremental policy support trickles-in. We see this combined with slight loosening on COVID quarantine guidelines as supportive for the coming months, barring widespread deterioration of virus conditions. Still, the smaller increase in manufacturing output of just 0.6pts speaks to the limitations on the credit push from a demand perspective and a more targeted nature. Meanwhile, speculation on prospects for U.S. tariff relief continues in the background. While not our base case, select removal on non-strategic products and reduction on consumer goods could add an estimated 0.25-0.4% pts to annual growth.
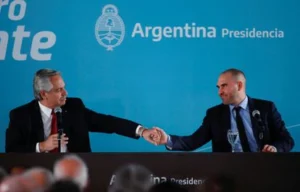
Argentina receives IMF board approval on 1st program review; FX pressures abate amid new controls
Following a staff-level agreement earlier this month, the IMF Board approved the first review as expected and disbursed 4 billion USD, which following repayments to the fund in June (already made) and July will result in a net decline in FX reserves of 450 million USD.
Domestic financing conditions were under strain heading into the large maturities at month-end but with BCRA support in the secondary market, conditions were able to roll successfully. With pressured net FX reserves in a strained external and domestic backdrop, the authorities tightened FX controls on imports and extended the measures through September. The gap between the parallel and official rates hovered around 100% for most of the week up significantly from an average of 80% in May but down from the peak of 120% touched mid-month.
We see the IMF review as constructive but with lingering uncertainties that will likely continue to drive asset price volatility. Despite interim revisions, program targets remain difficult to achieve in the context of a domestic market that will likely remain under pressure with maturities picking up again in late July and peaking in September and little FX reserve support aside from BOP control tactics. Our base case remains for patience and flexibility from the Fund with potential for tweaks on the fiscal side and greater leniency allotted on Central Bank financing to avoid arrears. With that being said, macroeconomic and political dynamics are increasingly fragile leaving uncertainty high. All else equal, the current backdrop continues to favor political change over the medium term with polls showing growing opposition support.
Stay up to date
More Newsletter to Check



SUBSCRIBE TO NEWSLETTER
Subscribe to download our daily economics and business roundup


×
![]()