
2024 investment outlook: threading the needle

2024 investment outlook: threading the needle
Investors face tough choices in an imperfect world, but can look for opportunities in fixed income while remaining cautious on emerging markets and commodities. Investors will need to make deliberate choices in 2024, paying close attention to monetary policy if they want to avoid a variety of potential pitfalls and find opportunities in an imperfect world of cooling but still-too-high inflation and slowing global growth. Markets have already baked into asset prices the idea that central banks will nail a smooth transition to reduced levels of inflation—meaning there’s limited runway for increased valuations. But 2024 should be a good year for income investing, with Morgan Stanley Research strategists calling bright spots in high-quality fixed income and government bonds in developed markets, among other areas. Central banks will have to get the balance correct between tightening just enough and easing quickly enough. For investors, 2024 should be all about threading the needle and looking for small openings in markets that can generate positive returns.
Getting through the last stretch of inflation is likely to lead to slower growth, particularly in the U.S., Europe and the UK. Meanwhile, China's tepid growth will weigh on emerging markets, and there's a risk that the country's economy could get sucked into a wider debt-deflation spiral, with ripple effects for the rest of Asia and beyond. Morgan Stanley predicts that China will avoid the worst-case scenario, and that U.S. and European policymakers will begin cutting rates in June 2024, improving the macroeconomic outlook for the second half of the year. In 2023, equity markets showed strong performance as they recovered from the recession fears that fed into the October 2022 trough, proving more resilient than analysts expected. However, 2024 is likely to be a “tale of two halves,” with a cautious first half giving way to stronger performance in the second half of the year.
For the first half of 2024, strategists recommend that investors stay patient and be selective. Risks to global growth—driven by monetary policy—remain high, and earnings headwinds may persist into early 2024 before a recovery takes hold. Global stocks typically begin to sell off in the three months leading into a new round of monetary easing, as risk assets start pricing in slower growth. If central banks stay on track to begin cutting rates in June, global equities may see a decrease in valuation early in the year.
In the second half of the year, however, falling inflation should lead to monetary easing, bolstering growth. It is expected that near-term uncertainty will give way to a comeback in U.S. equities. Throughout the year, however, there should be a few constants. Overall, U.S. equities are likely to have fair returns and better outcomes than European or emerging-market stocks. This becomes especially true if these economies don’t manage a soft landing. In that case, it is likely to see a flight to quality in which the U.S. outperforms. Emerging-markets equities face obstacles, including a strengthening dollar and lackluster growth in China, where policymakers face the triple challenges of debt, demographics and deflation. These risks are compounded by the corporate focus on diversifying supply chains amid geopolitical tensions and the fallout from pandemic-era disruptions. However, emerging markets could see stronger recovery in the second half as lower rates and a weakening U.S. dollar could prompt inflows.
One global bright spot is high-quality fixed income. Yields on a broad cross-section of U.S. corporate and government bonds reached 6%, the highest since 2009. U.S. Treasury and German Bund yields are the highest they have been in a decade, and Morgan Stanley forecasts 10-year yields on U.S. Treasurys at 3.95%, and DBR at 1.8% by the end of 2024.
2024 Macroeconomic outlook: central banks look for “just right” on rates
With inflation cooling, central banks around the world face a Goldilocks dilemma: If they are too easy with monetary policy, inflation could come roaring back; but if they keep policy too tight, it could trigger a recession.
As central bankers try to maneuver a “soft landing,” Morgan Stanley economists expect their efforts will come with a tradeoff: lackluster growth in 2024 and 2025, especially in developed markets. “Inflation has peaked globally, but getting through the last stretch won’t happen until 2025 and will likely require a period of subpar growth,” says Seth Carpenter, Global Chief Economist at Morgan Stanley. It is predicted that global economic expansion will tick down to 2.8% in 2024 and 2.9% in 2025, from 3% in 2023. In 2023, central banks successfully tamped down price gains by ratcheting up interest rates, slowing the pace of inflation to mid-to-low single digits. Heading into 2024, inflation should continue to fall in developed markets, while emerging markets may see a more gradual letup due to the volatility of food and energy prices. “The decline of inflation in 2024 should be much more gradual than in 2023, as inflation is close to—but not quite at—target in most developed market economies,” Carpenter says.
Overall, it is expected that growth in developed markets to remain broadly soft with a mixed picture in emerging market growth. Here’s a closer look at Morgan Stanley’s outlook for growth across regions: In the U.S., growth should slow to 1.9% year over year in 2024 and 1.4% in 2025, down from an estimated 2.4% in 2023, as higher interest rates and tighter monetary policy work their way through the financial system. Also, it is expected that the U.S. consumer spending to begin to slow more meaningfully in 2024 and 2025, driven by a cooling labor market, which weighs on real disposable income, and elevated rates putting further pressure on debt service costs. Among bright spots: business investment should finally turn positive in the second half of 2024 after two years of decline.
The Euro Area could eke out a gain of 0.5% in 2024, reflecting the ongoing effects of energy supply shocks, especially in Germany. Growth should accelerate to 1% in 2025, driven by inflation declines and a resilient job market, which may lift inflation-adjusted incomes and consumer spending. The UK is likely to experience a near-term drag following healthcare and transport strikes. The economy could dip into a technical recession at the beginning of 2024, with a 0.5% gain by the end of the year, picking up to 1% in 2025. Emerging markets present a mixed picture, with expansion in India, Indonesia and the Philippines counterbalanced by tepid growth in China, which has disappointed on post-COVID reopening recovery and growth expectations. Our economists see a bumpy path back to stable growth but expect the government to respond with policies to stimulate ethe economy.
For Japan, significant nominal growth is expected (5.4% in 2023) amid the economy's great escape from the lost decades. However, wage growth and strong domestic inflation should keep nominal GDP growth at 3.6% in 2024. Real GDP growth (after factoring in inflation) should be 1% in 2024, and 1.1% in 2025. In Central Europe, the Middle East and Africa, Poland should start to recover, with 3.4% growth in 2024, up from 0.7% this year. Growth will pick up in Hungary and the Czech Republic, while Turkey will see a slowdown. In Israel, the impact of the conflict in Gaza should be contained to the fourth quarter of 2023, followed by a swift recovery in the first three months of 2024.
In Latin America, Morgan Stanley forecasts muted growth in Brazil, with real GDP growth of 1.7% in 2024 and 1.6% in 2025, down from an estimated 3.1% in 2023. Growth in Mexico is likely to be 2.3% in 2024 and 2.2% in 2025, down from an estimated 3.4% in 2023, as strong labor markets and remittances boost consumption, and near-shoring continues to bolster the economy. Chile's economy will rebound, Colombia will see a slowdown and the recession in Argentina will likely deepen.
Turkey raises interest rates for fifth time in as many months
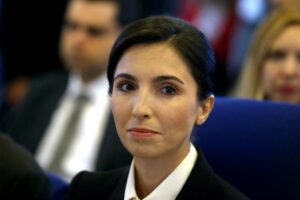
Central bank’s efforts to bring down inflation could be complicated by any escalation of Israel-Hamas conflict. Turkey has raised interest rates for the fifth time since June as the country steps up its battle against inflation and the threat of escalating conflict in the Middle East poses a fresh challenge to policymakers. The central bank on Thursday increased the benchmark one-week repo rate by 5 percentage points to 35%. The big rate rise is the latest sign of how Turkey has sharply pivoted its economic policy since President Recep Tayyip Erdoğan was re-elected in May. Central bank chief Hafize Gaye Erkan has vowed since her appointment in June to tighten monetary policy as much as is necessary to cool inflation, which is running at more than 60%.
“Monetary tightening will be further strengthened as much as needed in a timely and gradual manner until a significant improvement in inflation outlook is achieved,” the central bank said, as it warned that “geopolitical developments pose risks to the inflation outlook” if they led to higher oil prices. The price of international crude benchmark Brent has jumped nearly 20% to $88 a barrel since the start of June. Production and export cuts by Saudi Arabia and Russia have partly driven the rally. But analysts also fear that any broadening of the Israel-Hamas war into a wider regional conflict will send prices even higher.
Turkey imports the bulk of its energy and, in addition to boosting inflation, higher oil prices will make it more difficult for the government to achieve its goal of narrowing the country’s massive current account deficit. Higher rates are part of a broader economic overhaul that is being led by finance minister Mehmet Şimşek, who was appointed in June. The government has boosted taxes, taken a series of actions to slow consumer and commercial lending growth and allowed the lira to fluctuate more freely after curtailing a costly programme to prop it up.
Foreign investors, who fled Turkey after years of unorthodox economic policies, have broadly taken an upbeat view on the new programme even if they remain sceptical about how much leeway policymakers will have ahead of next year’s municipal elections. Investors are also paying keen attention to Erdoğan’s response to the Israel-Hamas conflict. The Turkish president has stepped up his rhetoric against the Jewish state and its western allies in recent days. Turkish stocks fell sharply on Wednesday after he said Hamas, whose militants killed at least 1,400 people in its October 7 attack on Israel, was not a terrorist organisation but rather a “group for liberation”.
Hamas, Israel ready for more hostage releases as truce holds
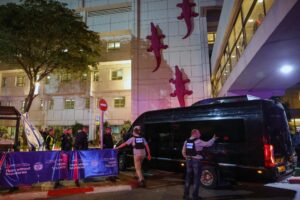
Hamas, Israel prepared for a third day of hostage releases from Gaza, after a last-minute dispute on Saturday threatened to derail a fragile truce. Dozens of Palestinian and Israeli prisoners have been released in the first 48 hours of a four-day ceasefire that is also allowing vital supplies of aid and fuel into Gaza. Since Friday, Hamas has freed 26 Israelis and 15 foreign nationals and Israel has released almost 80 Palestinians under the terms of the agreement, which was brokered by Egyptian and Qatari negotiators during weeks of talks. Some 150 Palestinians, 50 Israelis, and an unknown number of foreign nationals will be freed during the truce, which expires on Tuesday morning. Almost all of those released have been women, children and the elderly. A bump in the road: Day two of the hostage release didn’t go according to plan, getting held up for several hours following a dispute between the two sides. Egypt helped resolve the impasse, Diaa Rashwan, head of Egypt’s State Information Service, said.
The first two days of the ceasefire have allowed medical aid, food, water and fuel into Gaza after supply levels neared zero last week. Aid trucks have increased to around 200 per day, though this remains far below the 500 trucks that crossed the border before the war, with the Palestinian Red Crescent saying yesterday that it does “not even scratch the surface” of the needs of Gaza’s 2.3 mn population. Israel is also allowing 130k liters of fuel a day into the enclave yet this is still just over 10% of pre-war volumes. An extended temporary truce could be in the cards: Egypt had received ‘positive signs’ of a one- or two-day extension on the ceasefire during intensive negotiations, which would also spell out the release of more hostages in Gaza and Palestinian prisoners in Israeli prisons, Rashwan said yesterday. Under the truce, Israel agreed to extend the ceasefire by one day for every 10 additional hostages released by Hamas.
The likelihood this will be anything other than temporary is remote. Israeli officials have been at pains to emphasize that the truce is temporary and that they will resume their devastating air and ground assault on Gaza in a few days. Defense Minister Yoav Gallant reiterated his goal to completely destroy Hamas and said the IDF could continue the war for another two or three months. Despite growing diplomatic pressure on Israel from allies: Officials from several European governments have used the lull in the fighting to intensify their criticism of Israel’s war, with the Spanish prime minister accusing it of indiscriminate violence and calling for a Palestinian state at a press conference at the Rafah crossing (watch, runtime: 17:35). In return, Israel accused Spain and Belgium — whose prime minister was also at the presser — of supporting terrorism. The UK has adopted a more critical tone, with the country’s new foreign secretary David Cameron calling the expulsion of Palestinians in the West Bank by extremist settlers “completely unacceptable.”
El Sisi calls for demilitarized Palestinian state: A future Palestinian state could be demilitarized, with international forces temporarily in place to guarantee security for Egypt and Israel, President Abdel Fattah El Sisi told a press conference in Cairo on Friday. “We said that we are ready for this state to be demilitarized, and there can also be guarantees of forces, whether Nato forces, UN forces, or Arab or American forces, until we achieve security for both states, the nascent Palestinian state and the Israeli state," he said, alongside the Spanish and Belgian prime ministers.
Stay up to date
More Newsletter to Check


SUBSCRIBE TO NEWSLETTER
Subscribe to download our daily economics and business roundup


×
![]()