
Next year’s unpleasant choices confronting the Fed

Next year’s unpleasant choices confronting the Fed
Central bank might stick officially to 2% inflation target but, in practice, pursue a higher one.
Signaling the pursuit of an objective while quietly heading in a different direction is a tactic in politics that is as old as it gets. Now the US Federal Reserve may be forced to consider such a tricky manoeuvre as 2023 unfolds. This is not because it is an optimal approach. Far from it. Rather, the Fed may end up seeing it as better than the other main options, now that it has fallen well behind an inflation process that is likely to prove stickier than many currently expect, including the central bank.
Since 2012, the Fed has been publicly and explicitly committed to a 2% inflation target. The 2% objective originated in New Zealand in 1990 and gradually spread to several other advanced countries. The target was deemed high enough to allow for the price adjustments needed for the economy’s desirable resource reallocations, while avoiding the zero lower bound trap where, it was thought, interest rates can no longer be cut further to stimulate the economy. And it was deemed low enough to stabilise inflationary expectations.
For a while now, inflation has been running significantly above the Fed’s target. While the Personal Consumption Expenditures Price Index (PCE), its preferred inflation measure, has been declining in recent months, it remains three times the target. Also worrisome is the morphing of the inflation process. No longer dominated by energy and food prices, the drivers of inflation are increasingly coming from the services sector. Within that sector, the latest monthly US payrolls data showed wages gaining 0.6% in November, twice the consensus forecast and taking the steadily increasing three-month moving average to 6%.
This accelerating wage growth was accompanied with robust monthly job gains. Persistently high job vacancies still outnumber the unemployed by a factor of 1.7 amid declining labour force participation. Combined with input price inflation that is declining slower than consensus forecast, there is reason from services alone to worry that inflation may well continue to overshoot Fed forecasts that have already been consistently revised up. There are also others, including the rewiring of global supply chains, the changing nature of globalisation and the energy transition. And, of course, the Fed is still playing catch-up to tame rising prices after its protracted gross mischaracterisation last year of inflation as “transitory” and its initially timid steps to withdraw monetary stimulus.
Rather than fall to 2-3% by the end of next year, US core PCE inflation will probably prove rather sticky at around 4% or above. This is what happens when an inflationary moment is allowed to get embedded into the economic system. The world’s most powerful central bank is now confronted with two unpleasant choices next year: crush growth and jobs to get to its 2% target or publicly validate a higher inflation target and risk a new round of destabilised inflationary expectations.
The appropriateness of the 2% inflation target itself is, of course, an issue. It is far from obvious that the Fed would opt for it were it to start afresh today. A target of 3-4% would ultimately be more likely, given the fluidity of the supply side, the energy transition, the required resource reallocations and, of course, the experience with the zero lower bound in the decade of the 2010s. Given all this, it could prove tempting for the Fed to continue to signal a 2 per cent inflation target but, in practice, end up pursuing a higher one hoping that the public will accept it over time as indeed a superior and stable objective.
This, of course, is far from an optimal approach. It is hard to pull off and involves delicate ethical issues that might raise more questions about the Fed’s accountability, credibility and autonomy. Yet, given the extent of economic uncertainty and financial fragilities, the Fed could end up thinking that this far from perfect policy approach may be the better course of action.
Here, we must say that an initial set of poor decisions often makes it very difficult to return quickly to an optimal place despite best intentions and efforts to do so. This, unfortunately, is the trap the Fed has fallen into owing not only to its two 2021-22 policy mistakes but also to its over-reliance on unconventional policies in the decade that preceded that. Unfortunately for all of us, its road from here does not get much easier any time soon despite the fall in inflation.
The ECB’s tone surprised markets with its hawkishness!
Especially in the context of other major central banks that appear to be signaling that the end of their respective hiking cycles might be getting closer.
In addition to a 50bps rate hike, the ECB also delivered a message pointing to a strong determination to continue hiking interest rates on the back of inflation forecasts that were revised higher, a willingness to remain in restrictive territory as long as necessary to tame inflationary pressures and the start of quantitative tightening. In reaction, risk-off sentiment prevailed, European sovereign bonds came under heavy selling pressure and the EUR/USD fluctuated around 1.06, as the USD appeal as a safe haven resurged amid increased risk aversion.
This marked a reversal in sentiment that was boosted earlier in the week by U.S. CPI data surprising to the downside in November for a second consecutive month. US CPI inflation data for November came in better than expected. Headline inflation (MoM) rose only 0.1% and core 0.2%, compared to the consensus forecasts of 0.3% for both. Annual inflation rates are now down to 7.1% and 6.0%, for headline and core respectively. As expected, both stock and bond markets are reacting well across the board to this better-than-expected economic news. This supported the view that inflation has likely peaked, and the Fed could slow the pace of rate hikes, despite Chair Powell’s relatively hawkish comments following the well telegraphed and expected 50bps hike by the FOMC on Wednesday.
For its part, the Bank of England (BOE) said that inflation has likely peaked as it lifted interest rates to the highest level in fourteen years. In emerging markets, inflation continued to trend lower from high levels across CEE, adding a downside surprise in Romania to the ones seen the prior week in the Czech Rep and Hungary. The HUF outperformed as Brussels released EU funds to Budapest despite on and off tensions. The central banks in Mexico and Colombia hiked rates, in line with expectations. Oil rallied, supporting EM and U.S. HY outperformance.
UK private sector wage growth accelerates
Pay rose 6.9% in three months to October but fell in real terms because of inflation.
Wage growth in the UK’s private sector accelerated in the three months to October as inflation rose into double digits, according to data which promises to fuel an increasingly bitter stand-off between ministers and unions. Annual growth of 6.9% in regular weekly earnings, excluding bonuses, was the highest outside the pandemic period in the private sector, the Office for National Statistics said on Tuesday — although workers have seen their pay fall sharply in real terms as consumer prices have risen even faster. Public sector workers have suffered a much bigger hit to living standards, with their earnings growing by just 2.7% over the same period, one of the biggest gaps recorded between the private and public sectors.
The figures reinforced worries at the Bank of England, by raising interest rates again last Thursday, that a tight labour market is driving wage growth to a level that is incompatible with its 2% inflation target. But they also show that this is almost entirely because of private sector wage deals. The government has argued that it cannot improve public sector pay offers, for fear of further fuelling inflation. Jeremy Hunt, the chancellor, said in response to the figures that the government’s plans would “help to more than halve inflation next year” but that this would require “some difficult decisions now”, adding: “Any action that risks embedding high prices into our economy will only prolong the pain for everyone.”
The worsening economic outlook is starting to affect the jobs market, with vacancies falling for a fifth consecutive quarter and unemployment edging up 0.1 percentage point from the previous quarter to 3.7%. Expectations of lower turnover putting less pressure on employers to recruit, while employees are becoming more cautious to move jobs. However, this still left the jobless rate close to record lows, with one position vacant for every unemployed jobseeker. Moreover, the rise in unemployment was partly because people who had previously dropped out of the labour market were starting to look for work again — a development that will be welcomed by policymakers, after a period in which rising economic inactivity has been fuelling wage pressures.
The economic inactivity rate fell 0.2 percentage points on the quarter to 21.5% as people aged 50 to 64 who had previously said they were retired began to return to the workforce. The employment rate increased by 0.2 percentage points on the quarter to 75.6%, although it still fell short of its pre-pandemic levels.
Elon Musk seeks to sell Twitter shares in search of new funds
Investors approached to purchase stock at 54.20 USD buyout price as social media company bleeds cash.
The head of Elon Musk’s family office has approached investors who helped the billionaire buy Twitter for 44 billion USD in October to try and raise new funds as the social media company continues to bleed cash and faces heavy interest payments on its debts. Jared Birchall, a former Morgan Stanley banker, approached Twitter’s shareholders on Thursday afternoon, according to two people familiar with the matter. He offered new shares in the company at 54.20 USD — the same price Musk paid to take the company private. His note to investors, first reported by Semafor, said Twitter was “pleased to announce a follow-on equity offering for common shares at the original price and terms”, according to one person who received it.
The note did not specify how much Twitter expected to raise in the new fundraising effort, but said it aimed to close the fundraising by the end of the year. A second person whose firm received the offer said Musk had indicated the new capital would be used to fund an expansion of its business, including a “hiring spree” of programmers to build a “super app” that could process payments, among other services. Birchall and Musk planned to hold a series of calls with Twitter investors who want to increase their stake in the company, the person said.
Musk bought Twitter after a dramatic six-month legal row, funding the acquisition with about 13 billion USD of debt and outside equity capital of about 7 billion USD. But he has been racing to cut costs since then, including by laying off about half of Twitter’s staff, after advertisers fled the platform over concerns about his content moderation strategy, threatening its 5 billion USD-a-year advertising business. A number of high-profile investors wrote big cheques to help fund Musk’s Twitter buyout in exchange for equity stakes, including Sequoia Capital, Andreessen Horowitz, Oracle co-founder Larry Ellison and cryptocurrency exchange Binance.
Banks including Morgan Stanley, Bank of America and Barclays face significant losses on the financing package they provided. Twitter, which made a loss of about 221 million USD in 2021, has to pay annual interest of about 1 billion USD on the loan. Between Monday and Wednesday, Musk sold 3.6 billion USD in Tesla, the electric vehicle maker he founded and leads. It was his fourth sale of Tesla stock this year, bringing his total disposals to almost 40 billion USD. The sales came despite Musk saying there would be “no further TSLA sales” to support the Twitter deal back in April.
On Tuesday, Musk tweeted: “At risk of stating obvious, beware of debt in turbulent macroeconomic conditions, especially when Fed keeps raising rates.” The banks that underwrote the Twitter buyout debt are desperate to sell the high-risk loans on to credit investors and move it off their balance sheets. However, significant discounts demanded by investors would result in losses that could easily top 1 billion USD.
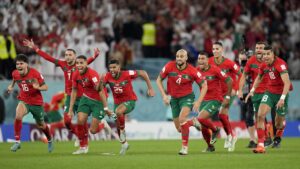
Morocco made history in Qatar by becoming the first African team to reach the final four of a World Cup
We join so many others in saluting Morocco for an amazing run that made history, earned the admiration of so many, and made us all proud and happy.
Along the way, the Moroccan team charmed many Arab soccer fans who saw in the team a reflection of themselves, with players waving the Palestinian flag after their wins and celebrating on the field with their mothers and children. Croatia departed the World Cup on Saturday with another medal, an extraordinary feat for a young country with a population smaller than some cities. Morocco left the World Cup with prizes that outweigh the outcome, a shining light for the Arab world and African soccer.
Led by captain Luka Modric, the celebration began on the field with the presentation of medals. Croatia, in all its checkerboard-uniform glory, rejoiced after another sterling performance on the world stage. Coach Zltako Dalic, a holdover from the 2018 championship appearance, hugged Modric and kissed him on the forehead. The match marked the end of Modric’s World Cup career after four tournaments. At 37, he started all seven matches here and conducted his team with elegance and class as Croatia, a nation of 3.9 million, continued defying international odds. The defeat failed to dampen Morocco’s month-long accomplishments. In becoming the first African team to advance to the semifinals, the Atlas Lions became the feel-good story of the World Cup and, following Croatia’s trendsetting march four years ago, inspired nontraditional programs. They also galvanized fans across Arab countries.
“Football makes people dream, especially children,” Coach Walid Regragui said. “We have allowed them to dream, kept the dream alive, and now they dream of being footballers and getting to the World Cup. That is priceless. It means more than winning any match.” For Morocco, a World Cup run that transcends the sport. Morocco was seeking to become the first non-European or South American team to finish in the top three since the United States was third at the 1930 inaugural tournament. The only other non-European/South American semifinalist was South Korea, which finished fourth in 2002. Initially, Moroccan players were crushed. But as a sea of supporters, many of whom had traveled from Morocco for the fantastic run in the knockout stage, saluted their effort, the Atlas Lions waved to the crowd. Their triumphs transcended all else.
Stay up to date
More Newsletter to Check


SUBSCRIBE TO NEWSLETTER
Subscribe to download our daily economics and business roundup


×
![]()